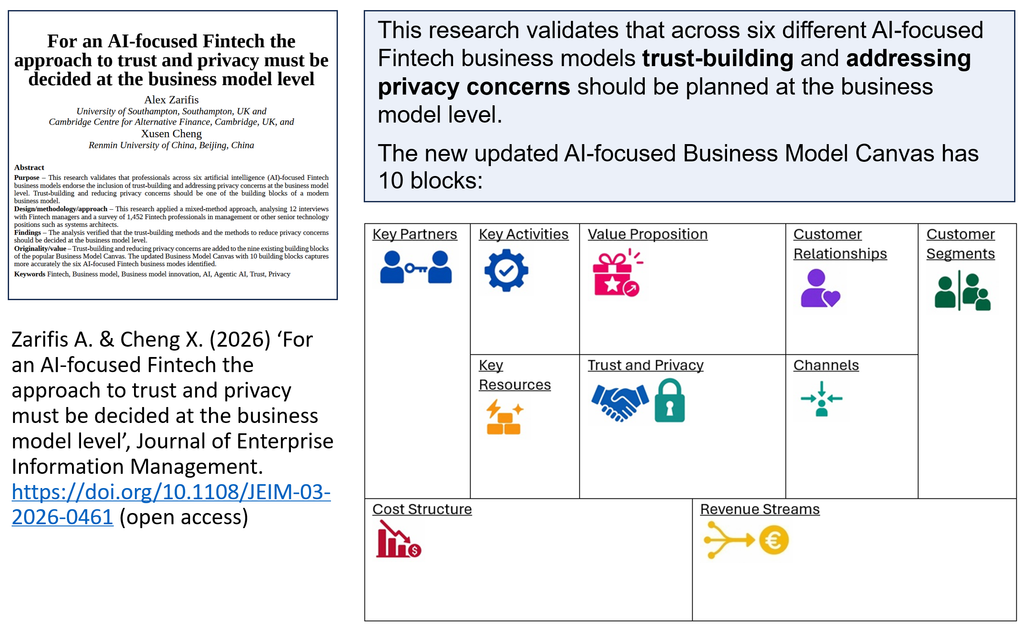
The widely used Business Model Canvas identifies nine building blocks of a business model. These nine building blocks did indeed capture the key priorities of a business model for many years. However, with the increasing role of AI and the increasing volume of data it consumes, some additions to these nine building blocks are necessary to bring them up to date. One more building block is added to capture the increased role of AI and data. The new building block captures the trust-building methods applied, and the methods utilized to reduce privacy concerns. Trust-building is added because of how central trust with all the stakeholders is to utilizing AI. Privacy concerns are important for legal and ethical reasons, but also because if users have these concerns, they will not share their data as willingly. These can be seen as two separate issues, but they are often intertwined. Both trust and privacy concern require a deep understanding of the user’s perspective. Insufficiently addressing trust and privacy can lead to pushback from customers, but also from governments in the form of stricter regulation, thereby negating the benefits of increased use of AI.
Table 1: The updated AI-focused Business Model Canvas with 10 blocks
This research tested the new building block against each of the six proven AI-focused business models. The first three models involve organizations that are already active in the financial sector. The last three models are organizations that are new to offering financial services. With the new building block added to the original Business Model Canvas, the resulting ten building blocks are: (1) value propositions, (2) customer relationships, (3) customer segments, (4) channels, (5) cost structure, (6) revenue streams, (7) key partnerships, (8) key activities, (9) key resources, and (10) how to build trust and reduce privacy concerns. These ten building blocks ensure that the stakeholders in an organization are focused on the most important issues when planning and implementing a new business model (Zarifis & Cheng 2026).
Reference Zarifis A. & Cheng X. (2026) ‘For an AI-focused Fintech the approach to trust and privacy must be decided at the business model level’, Journal of Enterprise Information Management. https://doi.org/10.1108/JEIM-03-2026-0461 (open access)
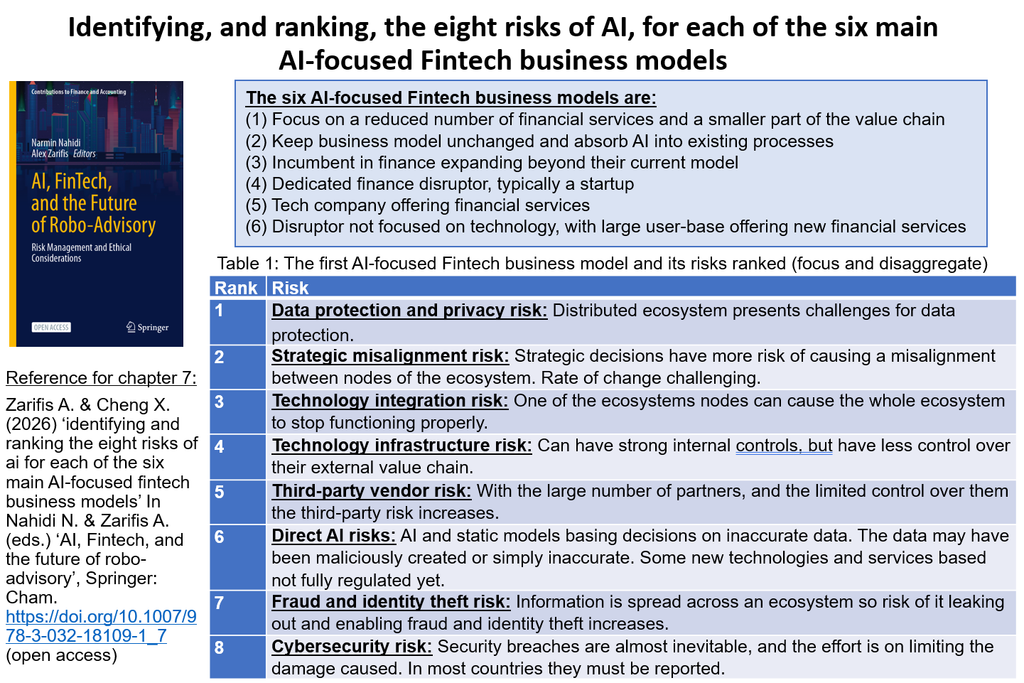
This research explores the implications for risk, of six AI-focused Fintech business models, identified in the previous research. While each of the six business models has been validated in previous research, their typical influence on risk has not been sufficiently explored The first three of the six AI-focused finance business models, apply to existing financial companies. These are (1) concentrating on a reduced number of financial services, and a smaller part of the value chain, (2) keeping the business model unchanged, and absorbing AI into existing processes, and (3) expanding beyond their current model, without sacrificing existing services. The last three AI-focused Fintech business models, apply to organizations that did not previously offer financial services. So, the last three are (4) a dedicated finance disruptor, typically a startup, (5) a tech company offering financial services, and finally (6) is a disruptor not focused on technology, with large user-base offering new financial services.
Table 1. The first AI-focused Fintech business model and its risks ranked (focus and disaggregate)
The eight risks related to the application of an AI-focused business model identified are: (1) Direct AI risks, (2) technology integration risk, (3) third-party vendor risk, (4) technology infrastructure risk, (5) data protection and privacy risk, (6) cybersecurity risk, (7) fraud and identity theft risk, and finally (8) strategic misalignment risk. The eight risks apply to all six models, however, they are not equally significant in all models. For example, in table one we see the ranking of the eight risks for the first AI-focused business model. The six business models reduce risk in two main ways: Firstly, because they are proven models, and secondly because they have a proven place in the emerging financial ecosystem. While the Fintech business models do not necessarily increase risk, and may indeed reduce it, because of the change in the nature of the risk involved, trust needs to be built with all the stakeholders. These are the main findings of this research.
Reference for chapter 7: Zarifis A. & Cheng X. (2026) ‘Identifying and ranking the eight risks of AI for each of the six main AI-focused Fintech business models’ In Nahidi N. & Zarifis A. (eds.) ‘AI, Fintech, and the future of robo-advisory’, Springer: Cham. https://doi.org/10.1007/978-3-032-18109-1_7 (open access)
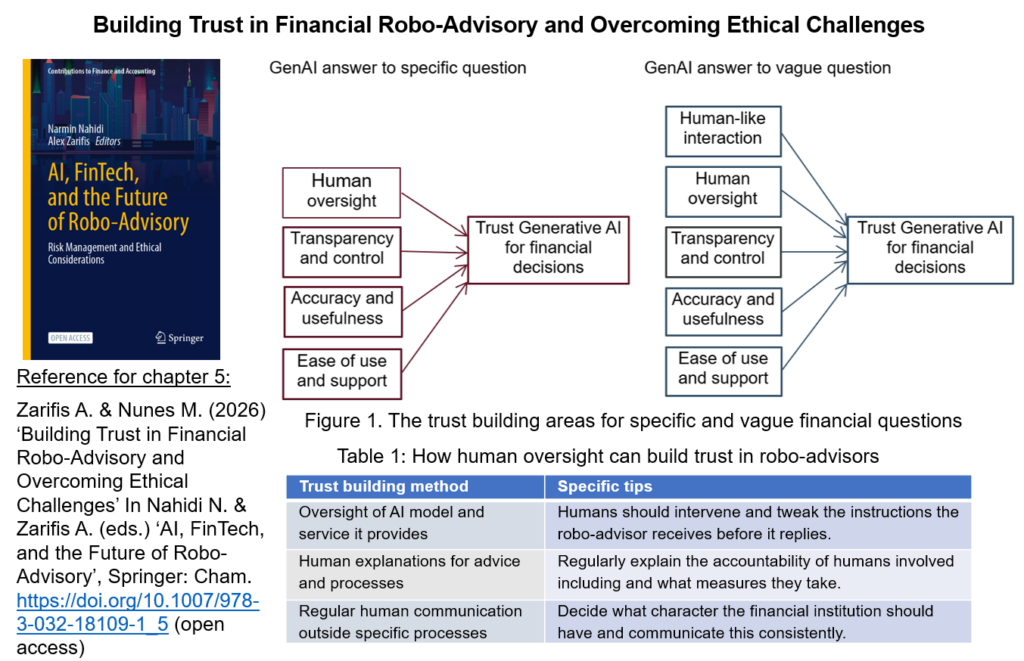
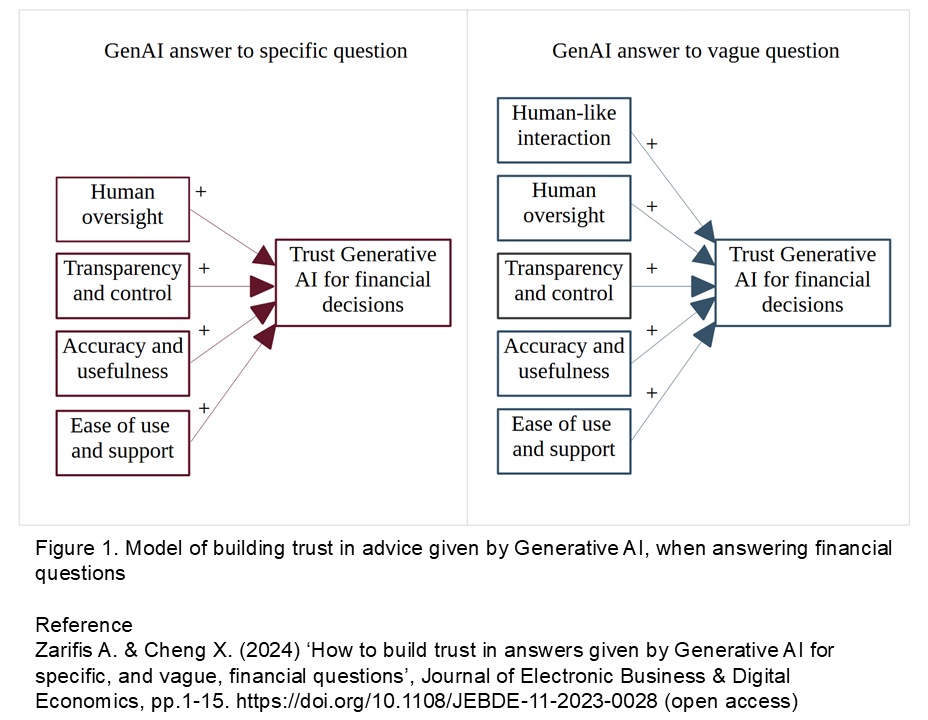
Most financial institutions can meet their short-term targets by offering attractive services. However, the best financial institutions go beyond that, and build strong relationships. Both retail customers and organizations, show trust and loyalty to financial institutions they have a stronger bond with. Before the internet, this happened naturally with the face-to-face interaction. Even when we interacted with a company’s systems on the internet, until recently, these systems did not use AI, but human logic coded into them. Now, with the prevalence of AI and financial robo-advisory, new ways are needed to build trust. Previous research identified five areas where trust could be built for financial robo-advisors, as illustrated in figure 1. These are building trust with human oversight, with transparency and control, with accuracy and usefulness, by making things easy to use, and finally with a humanlike interaction. This research identifies the specific methods for building trust, for each of these five areas.
Figure 1, the trust building areas for specific and vague financial questions and table 1, building trust with human oversight
Previous research identified five areas where trust could be built for financial robo-advisors, as illustrated in figure 1. This research identifies the specific methods for building trust, for each of these five areas. For example, as illustrated in table 1, building trust with human oversight can be done in three specific ways: (1) Oversight of AI model and service it provides, (2) human explanations for advice and processes, and (3) regular human communication outside specific processes. Building trust with transparency and control can be done by: (1) Recognizing that there are beliefs that do not immediately lead to action, so following the current data will not give us all the answers, (2) explain actions and demonstrating ability and integrity, and (3) balance automation with control to avoid disempowering users. Building trust with accuracy and usefulness can be done by having: (1) Accurate and relevant information conveying competence and integrity, (2) useful functionality supported by extensive testing, and multiple methods, and (3) enhanced usefulness through personalisation. Building trust by making things easy to use can be done by: (1) Making everything easy to use while keeping all the necessary functionality, (2) support time management with nudges, and (3) having a useful and reliable service with high performance. Building trust with a humanlike interaction can be done by: (1) Utilizing the latest sentiment analysis, and longest contextual memory, (2) the robo-advisor should have a clear persona, and (3) build a relationship, and a feeling of friendship and partnership.
Reference for chapter 5: Zarifis A. & Nunes M. (2026) ‘Building Trust in Financial Robo-Advisory and Overcoming Ethical Challenges’ In Nahidi N. & Zarifis A. (eds.) ‘AI, FinTech, and the Future of Robo-Advisory’, Springer: Cham. https://doi.org/10.1007/978-3-032-18109-1_5 (open access)
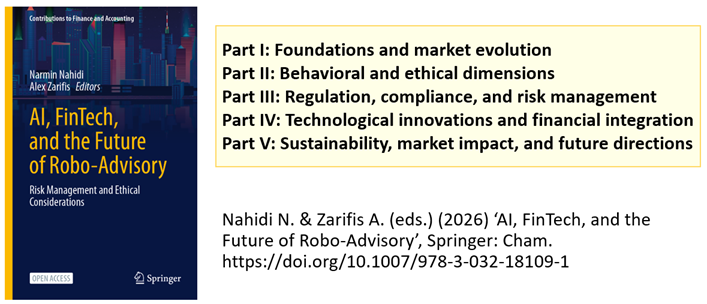
Among the many Fintech innovations, robo-advisors offering algorithm-based financial planning and investment services are rapidly rising to prominence. Their emergence signals a shift not only in how financial advice is delivered, but also in the broader relationship between finance, technology, and society. Robo-advisors are digital platforms that offer investment advice and typically create customized portfolios for individuals based on their preferences. These automated investment advisors are guiding an increasing volume of people and resources. They are growing in their ability and influence. The AI used can draw on a huge breadth of data and identify patterns that a human would miss, and may even defy a rational explanation. Despite the potential they have, in practice, customization is often limited and the investors are simply put in a number of categories based on their dispositions to risk and their goals. The state of the art of what AI can do in this context and what is offered can be quite different, with some simpler services riding the wave of popularity of AI. This book covers the key issues related to robo-advisors covering both the financial and technological dimensions. It has five parts and 15 chapter covering many different aspects of this solution. The first part is on the foundations and market evolution, the second covers behavioural and ethical dimensions, the third discusses regulation, compliance, and risk management, then we look at technological innovations and financial integration, and finally, we explore sustainability, market impact, and future directions.
Using robo-advisors effectively may involve using the latest versions of generative AI or applying completely commoditized solutions with an effective business model. There isn’t one answer, but it is necessary to understand this service and more broadly the role of Fintech in disrupting finance. To be successful, those coming from finance must understand robo-advisors as a technology and as an innovation, while people from a technology background must understand the financial dimension. In addition to the typical service of portfolio management, other common services are retirement planning, financial planning tools, fractional share investing, thematic and ESG investing, dividend reinvestment, crypto investments, estate planning, insurance advice and debt management.
Reference for book: Nahidi N. & Zarifis A. (eds.) (2026) ‘AI, FinTech, and the Future of Robo-Advisory’, Springer: Cham. https://doi.org/10.1007/978-3-032-18109-1 (open access)
Reference for first chapter: Zarifis A., Nahidi N. & Yarovaya L. (2026) ‘The Rise of Robo-Advisory in FinTech’ In Nahidi N. & Zarifis A. (eds.) ‘AI, FinTech, and the Future of Robo-Advisory’, Springer: Cham. https://doi.org/10.1007/978-3-032-18109-1_1 (open access)
Belmont Road in Southampton has some Victorian terrace houses, and some large, detached houses, some have even been referred to as ‘Grand Victorian’. If you drive through without paying much attention you would think it is a middle to upper class neighbourhood, an impression reinforced by the Sainsburys and Waitrose not too far away. However, if you look closer, some details suggest otherwise. The streets are permanently dirty with all kinds of rubbish, most of the large houses are divided into many small flats, and the ‘for sale’ signs seem far more than normal. Why are so many people leaving?
I had been an army officer which develops your ability to assess danger, probably to the point of paranoia. Without wanting to, you assess the danger of every place you are in. In the army, what scared us was not the clear dangers, we knew what to do in those situations, and of course we knew what to do when there was no danger. What really scares you when you are in the army are the situations that lull you into a false sense of security. Belmont Road has just enough going for it to lull you into a false sense of security.
In the short time I was there I saw many crimes and tried to get the police interested several times. The night Henry Nowak was murdered I heard some horrible screams that sounded like someone was being stabbed. I told myself I hope that is not as bad as it sounded but I knew.
The next morning Belmont Road was cordoned off. Initially we were told one 18 year old student attacked four people and that the police were trying to understand what happened AFTER that.
Some people put flowers, cards, and some other items such as a book of his team Arsenal. The items gave it a more personal touch than the usual flowers. These flowers and items were repeatedly vandalised. They were thrown on the floor, and it looked like they had been kicked and stamped on. Was this really about one murderer or was this something wider about this area? The murderer was in custody. Who were vandalising the flowers?
When there was a vigil in front of Portswood police station where some flowers and pictures were placed, there was a ‘counter protest’ by people claiming to be against racists! I never heard of a counter-vigil!
I walked past the point he was murdered on my way back from work on the day the court convicted the murderer, someone put white flowers and wrote on a piece of paper ‘Justice’. It was perfect, the right word for closure. On my way to work the next day someone smeared a pink ice cream bar over the paper, and it was now laying down crumbled up, instead of standing up against the tree where it was placed. They didn’t want the white piece of paper writing the word ‘Justice’ to be standing upright. Just like they did not want to see Henry Nowak standing upright.
Tim Berners-Lee, the creator of the world wide web, has released an important new book about the problems we face online and how to solve them. It is called This is for Everyone, meaning that the internet should be for all. The philosophy espoused in the book is that the internet should not be a tool for the concentration of power among an elite. He wants the internet to function in a way that maximises the benefit to society. His central idea, as he has written before, is that people should own their data. Personal data is any data that can be linked to us, such as our purchasing habits, health information and political opinions. Everyone owning their data is a radically different approach to what we have today where big tech companies own most of it. This change is needed for two reasons. The first is specifically about people’s right to privacy, so we don’t all feel like we live in a glass box with everything we do being monitored and having an effect on our careers and the prices we pay for services such as insurance. If AI is steered to make more money for an insurer it will do that, but it will not necessarily treat people fairly. The second reason is that in a world being shaped by AI and data, if we do not own our data, we will have no power and no say in our future. For most of human history, workers’ labour was needed, and this gave them some power to pursue a fairer deal for themselves. Most of us have the power to deny our valuable labour if we feel we are not treated fairly, but this may not have the same effect in the future. For many of us, in the highly automated AI driven world we are moving towards, our labour will not always be needed. Our data, however, will be very valuable, and if people own their data, they will still have a voice. When a tech giant owns our data, it holds all the cards. None of these ideas are new, but as with the creation of the world wide web, Berners-Lee excels in bringing the best ideas together into one coherent, workable vision. Many people have pet-hates about the internet, some dislike how algorithms sometimes promote controversial views, and others don’t like handing over more personal information for a service than what is necessary. His ability to see the bigger picture is due to the knowledge he has, having had a front row seat to the development of the world wide web from the start. But what would this look like? In practice, owning our data would mean having a data wallet app on our phone which internet companies might request access to. The internet companies could offer a small payment, or make their service free in exchange for the access. The individual could choose to manage access themselves on a case-by-case basis, or delegate the management of the data to a trusted third party such as a data union. Berners-Lee recommends two possible solutions to break free from the oligopolistic situation we are in. The first is for government to intervene and create the regulation that would maximise the social good of the internet limiting the power of big tech. This is highly unlikely in the United States where big tech is fully supported by the state. While a court in the US recently decided that Google had acted illegally to keep its monopoly status in search, it was not broken up under monopoly laws because it would be “messy”. Elsewhere, though, for instance in the EU and Australia, there is a concerted effort to limit the negative outcomes for society of the internet. The EU constantly updates its general data protection regulation so that it offers some protection to citizens’ privacy, while in Australia a world-first social media ban has been passed for children under 16. Berners-Lee’s vision would require governments to go further. He has repeatedly asked for governments to regulate big tech warning that failing to do so would lead to the internet being “weaponised at scale” to maximise profit not social good. The regulation would seek to broaden competition beyond a small number of giant tech companies. Beyond state intervention, Berners-Lee presents other ways forward. Perhaps, he contends, people themselves can begin building better alternatives. For example, more people could use social media such as Mastodon.social that is decentralised and does not promote polarising views. As he sees it, a key part of the problem is that we become tied into platforms run by the giants. Owning our data would go some way to having a fairer relationship. Instead of being locked into an increasingly small number of big tech firms this would open the door to new platforms offering a better deal. Berners-Lee created the Open Data Institute that tries to bring agreement on new online standards. He is promoting what he calls socially linked data and co-founded Inrupt that offers an online wallet to store all our personal data. This could include our passport, qualifications, and information about our health. This decentralised model would give people the ability to analyse their data locally within the wallet to gain insights on their finances and health, without giving their data away. They would have the option to share their data, but this would now be from a position of strength. Access would be given to a specific organisation, to use specific personal data, for a specific purpose. AI, even more so than the internet, gives power to whoever has the data. If the data is shared, so will the power. Unlikely, but you never know Despite proposing solutions, his vision is the underdog here. The chances of it prevailing in the face of big tech power are limited. But it is a powerful message that better alternatives are possible. This message can motivate citizens and leaders to push for a fairer internet that maximises social good. The future of the internet and the future of humanity are interwoven. Will we actively engage to shape the future we want, or will we be helpless passive consumers? The worsening or “enshitification” of services has become an almost inevitable part of the innovation cycle. Many of us now wonder when, not if the service we receive will start to degrade dramatically once we are locked in. There is dissatisfaction but this has not yet led to people changing their habits, possibly because there have not been better alternatives. Berners-Lee made the world wide web a success because his solution was more decentralised than the alternatives. People are now seeing the results of the overcentralised internet, and they want to go back to those decentralised principles. Berners-Lee has offered an alternative vision. To succeed it would need to support from both consumers and states. That may seem unlikely, but once, so did the idea that the world would be connected via a single online information sharing platform.
Article published in The Conversation, republished under Creative Commons licence.
Reference Zarifis A. (2025) ‘Tim Berners-Lee wants everyone to own their own data – his plan needs state and consumer support to work’, The Conversation. Available from: https://doi.org/10.64628/AB.yq5sssjr3
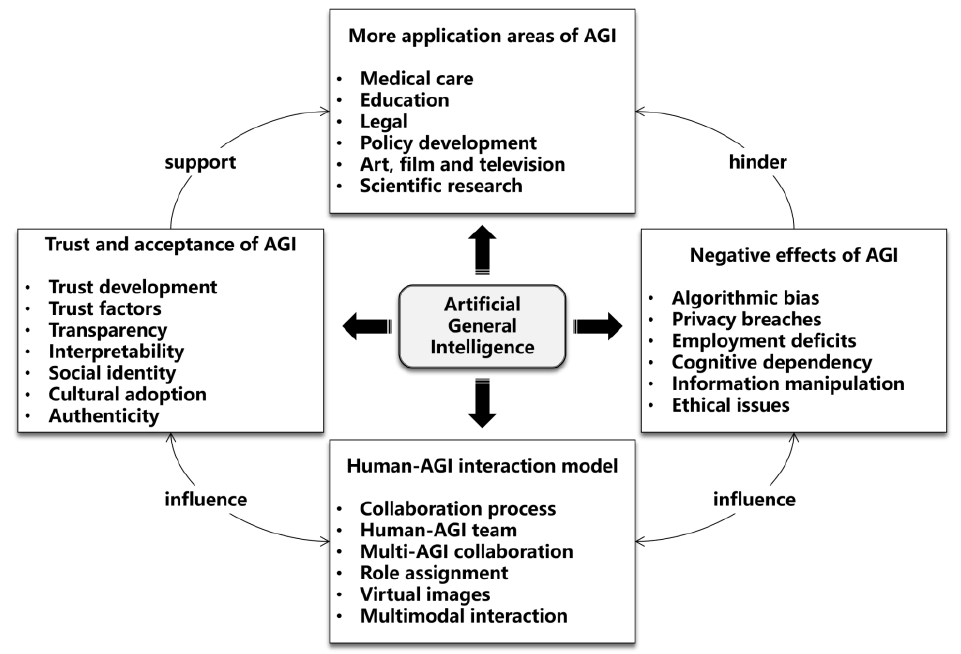
Artificial General Intelligence (AGI) can understand, learn, and apply knowledge across a range of tasks, in a similar way to humans. It is not limited to specific tasks. In e-commerce, AGI is revolutionizing the industry by enabling highly personalized shopping experiences, intelligent customer service, and efficient supply chain management. However, it also raises concerns about job losses and invasion of privacy (Cheng et al. 2025). Autonomous decision-making also has ethical implications.
Figure 1. Future trends in AGI research
In supply chain and operations management, AGI-driven tools like Deepseek can forecast demand better than before, coordinate logistics, and solve problems independently in real time. When organizations learn how to use these tools, they can adopt them faster and improve the overall supply chain performance. Alibaba’s smart warehouse demonstrates how AGI uses data, algorithms, and robots to automate inventory management, reduce errors, and enhance labour productivity through the collaboration between AI and human expertise. In marketing, AGI enables highly personalized strategies by creating content that resonates emotionally with customers. AI-generated virtual influencers with emotional expressions, such as happiness or surprise, can significantly increase user engagement, especially when combined with visually appealing content. AGI also excels at creating ads with agentic appeals, like messages focusing on efficiency. Consumers prefer these ads because they enhance the sense of self-efficacy in completing tasks. However, for ads that require emotional storytelling, human-AI collaboration remains crucial. Generative AI can also deliver highly personalized marketing content, outperforming traditional digital tools in terms of relevance and efficiency. In customer service, AGI-powered digital assistants build trust and encourage purchase intent by using anthropomorphic features. Computers become social actors. By improving response speed and problem-solving accuracy, AI chatbots can improve customer satisfaction and loyalty. Their effectiveness depends on balancing technical capabilities with human-like interactions. In industries such as hospitality and tourism, AGI tools like Deepseek can personalize recommendations and simplify backend operations, showing their adaptability across different sectors. A bibliometric review indicates that e-commerce AI research has long focused on recommendation systems, sentiment analysis, and personalization. Now, AGI is expected to integrate these areas into a cohesive, autonomous ecosystem. Collaborative AI frameworks emphasize combining AGI’s mechanical and thinking intelligence with human marketers’ intelligence. This allows humans to focus on strategic and emotional tasks while AGI automates routine processes.
Reference Cheng, X., Mou, J., Wang, Y., & Zarifis, A. (2025) ‘Development of AGI in e-commerce’, Journal of Electronic Commerce Research, vol.26, no.3, pp.163-169. http://www.jecr.org/node/737
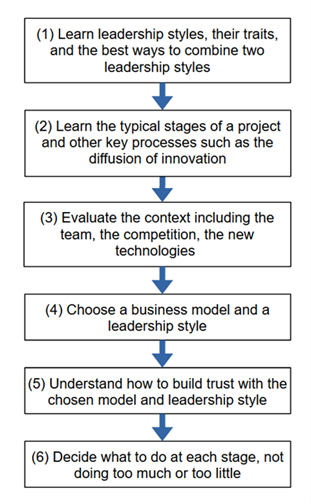
When we think of great leaders, we turn to famous leaders from history for inspiration, but they did not have to deal with unpredictable disruption AI is causing. The modern leader must not only lead humans, but also autonomous AI agents. They must also guide the organization through the process of adapting to fully utilize AI across all the operations. There is no simple answer to this challenge, but there is a structured approach with six steps that will increase the chances of success.
Figure 1. The steps to being a great leader in the age of AI
Step 1: Learn the three most effective leadership styles
The first step is to learn the three most effective leadership styles and understand the benefits of combining them in various ways. These are servant, transactional and transformational.
Step 2: Learn the typical stages of a project
The modern leader must constantly integrate the latest versions of AI so their role becomes similar to that of a project manager implementing a series of digital transformation projects. Typically, a project has six stages that are forming, storming, norming, performing, adjourning and post-project collaboration.
Step 3: Evaluate the context
While we are fascinated by the capabilities of AI, the role of the context the leader finds themselves in must not be underestimated. The leadership approach must consider the influence of the context on the people and the technology.
Step 4: Choose a business model and a leadership style
The leader needs to think about whether to focus on one of the three leadership styles or combine two of them to get the best out of the situation they are in.
Choosing a proven AI centred business model will offer clarity. There are six proven AI focused business models: first: incumbent focusing on one part of the value chain and disaggregating, second: incumbent absorbing AI into existing model, third: incumbent expanding beyond current model to fully utilise the opportunities of AI and access new data, fourth: startup disruptor focused on one sector, built from the start to be highly automated, fifth: disruptor focused on tech adding a new service such as insurance, and lastly the sixth model is a disruptor that is not tech-focused but has an extensive userbase.
Step 5: Build trust with a clear vision of what the role of AI is
To lead autonomous AI agents, the leader must build trust in them among the team. The leader must be clear on their use and build a consensus around this. The team must be put on a sustainable trajectory for change.
Step 6: Decide what to do at each stage of the project
Effective leadership today must involve leading on technology as well as people, building trust in the technology, and finding the best combination of leadership styles to get the most out of humans and automated AI agents. These many tasks cannot all be done at once so the leader must have a plan of what they will focus on at each stage.
The steps touched on here are covered more thoroughly in the book. If you want to learn more about Leadership in AI with trust you can buy my book from all good bookshops.
Fintech companies face the challenge of trying to lead in AI adoption while navigating potential pitfalls. The board of directors plays a critical role in demonstrating leadership and building trust with key stakeholders during the implementation of AI.
This research interviewed board members from Fintech companies to identify the most effective strategies for fostering trust among shareholders, staff, and customers. These three groups have different concerns and face different risks from AI. The findings reveal that the most effective methods for building trust differ among these three groups of stakeholders. Leaders should build trust for these three stakeholders in two ways: First, through the effective and trustworthy implementation of AI, and second, by transparently communicating how AI is used in a manner that addresses stakeholders concerns. The practical ways to build trust with the implementation and the communication for these three groups, shareholders, staff, and consumers, are presented in tables 1-3.
The findings show significant overlap between the effective overall implementation and governance of AI. However, several issues are identified that relate specifically to how AI innovations should be communicated to build trust. The findings also indicate that certain applications of Generative AI are more conducive to building trust in AI, even if they are more restrained and limited in scope, and some of Generative AI’s performance may be sacrificed as a result. Thus, there are trade-offs between unleashing Generative AI in all its capacity and a more constrained, transparent, and predictable application that builds trust in customers, staff, and shareholders. This balancing act, between a fast adoption of Generative AI and a more cautious, controlled approach is at the heart of the challenge the board faces.
Leaders and corporate boards must build trust by providing a suitable strategy and an effective implementation, while maintaining a healthy level of scepticism based on an understanding of AI’s limitations. This balance will lead to more stable and sustainable trust.
Table 1. How leaders can build trust in AI with shareholders
Implementation: 1) Use AI in a way that does not increase financial or other risks. 2) Build in-house expertise, don’t rely on one consultant or technology provider. 3) Make new committee focused on the governance of AI and data. Accurately evaluate new risks (compliance etc.). 4) Develop a framework of AI risk that board will use to evaluate and communicate risks from AI implementations. Management should regularly update the framework. 5) Renew board and bring in more technical knowledge and have sufficient competence in AI. Keep up with developments in technology. Ensure all board members understand how Generative AI and traditional AI work. 6) Make the right strategic decisions, and collaboration, for the necessary technology and data (e.g. through APIs etc.).
Communication: 1) Clear vision on AI use. Illustrate sound business judgement. Showcase the organization’s AI talent. 2) Clear boundaries on what AI does and does not do. Show willingness to enforce these. 3) Illustrate an ability to follow developments: Show similar cases of AI use from competitors, or companies in other areas. 4) If trust is concentrated on specific leaders that will have a smaller influence with the increased use of AI, the trust lost must be re-built. 5) Be transparent about AI risks so shareholders can also evaluate them as accurately as possible.
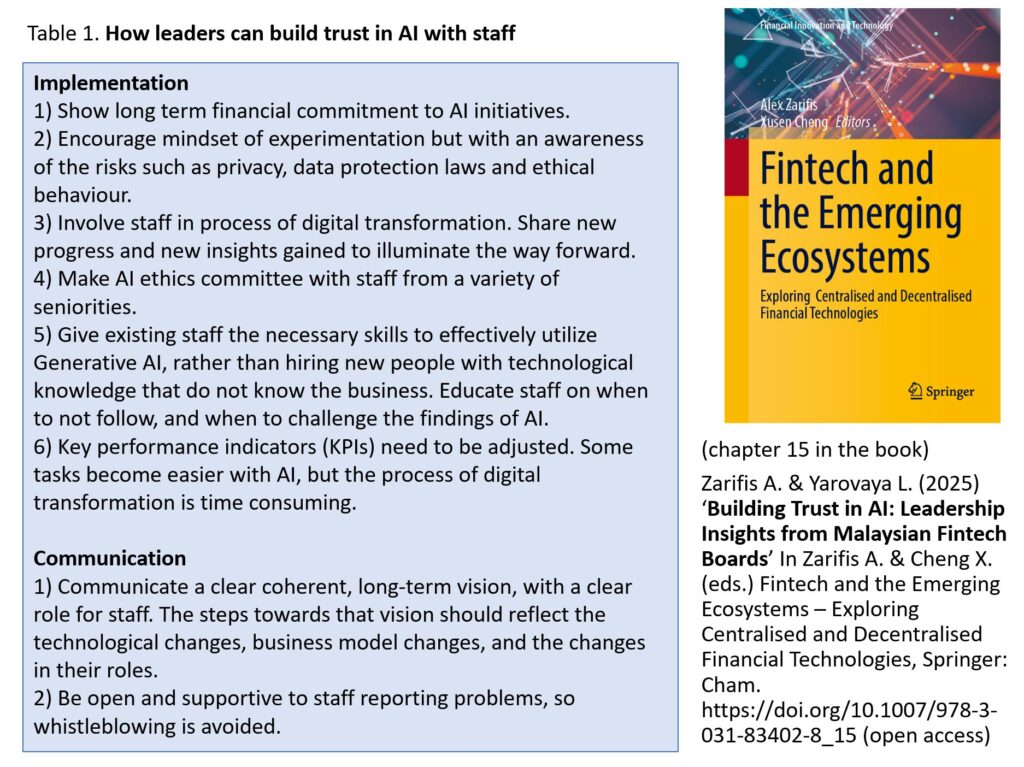
Table 2. How leaders can build trust in AI with staff
Implementation: 1) Show long term financial commitment to AI initiatives. 2) Encourage mindset of experimentation but with an awareness of the risks such as privacy, data protection laws and ethical behaviour. 3) Involve staff in process of digital transformation. Share new progress and new insights gained to illuminate the way forward. 4) Make AI ethics committee with staff from a variety of seniorities. 5) Give existing staff the necessary skills to effectively utilize Generative AI, rather than hiring new people with technological knowledge that do not know the business. Educate staff on when to not follow, and when to challenge the findings of AI. 6) Key performance indicators (KPIs) need to be adjusted. Some tasks become easier with AI, but the process of digital transformation is time consuming.
Communication: 1) Communicate a clear coherent, long-term vision, with a clear role for staff. The steps towards that vision should reflect the technological changes, business model changes, and the changes in their roles. 2) Be open and supportive to staff reporting problems, so whistleblowing is avoided.
Table 3. How leaders can build trust in AI with customers
Implementation: 1) Avoid using unsupervised Generative AI to complete tasks on its own. 2) Only use AI with clear transparent processes, and predictable outcomes, to complete tasks on its own. 3) Have clear guidelines on how staff can utilize Generative AI, covering what manual checks they should make. 4) Monitor competition and don’t fall behind in how trust in AI is built.
Communication: 1) Explain where Generative AI and other AI are used and how. 2) Emphasise the values and ethics of the organization and how they still apply when Generative AI, or other AI, is used.
The authors thank the Institute of Corporate Directors Malaysia for their support, and for featuring this research: https://pulse.icdm.com.my/article/how-leadership-in-financial-organisations-build-trust-in-ai-lessons-from-boards-of-directors-in-fintech-in-malaysia/
References
Zarifis A. & Yarovaya L. (2025) ‘Building Trust in AI: Leadership Insights from Malaysian Fintech Boards’ In Zarifis A. & Cheng X. (eds.) Fintech and the Emerging Ecosystems – Exploring Centralised and Decentralised Financial Technologies, Springer: Cham. https://doi.org/10.1007/978-3-031-83402-8_15 (open access)
Decentralized finance (DeFi) is becoming more and more popular. Decentralized exchanges (DEX) are a type of DeFi that allow users to trade freely and anonymously on a blockchain. There are two platforms for cryptocurrency trading, centralized exchange (CEX) and DEX. Most of the exchange volume is happening at CEX because they are easier to use. However, DEXs volume is catching up. The reasons for the popularity of DEXs are linked to the unique advantages of DeFi. First, CEX is a business that requires Know Your Customer (KYC). It requires customers’ identification for registration to comply with anti-money laundering regulations and any other laws from the countries its customers come from. Because of this, users are still concerned about several issues such as privacy and the risk of their wealth being confiscated. This study focuses on how external factors affect the adoption of DEXs and provides suggestions for the development of the entire DEX industry. The study finds that the expansion of the DeFi industry has a significant impact on the adoption of DEXs, so DEXs should cooperate to develop the industry instead of focusing on competing for a larger share of the existing market. Some other external factors also have an impact, such as technological innovation, partner integration and community support. As DeFi is closely related to the adoption of DEX, the study also discusses the external factors that may affect the adoption of DeFi, namely trust, infrastructure, and regulation.
Figure 1. The factors that affect the adoption of Decentralised Exchanges DEX
Related research is mainly focused on the difference between DEXs, and tries to find how a DEX can gain an advantage over other DEXs, but this research concentrates on the external factors to show how to encourage DEX adoption. While market fluctuations may attract short-term attention and reactions, the long-term development of DEX relies on a stable user base in DeFi and continued expansion of the industry. This research enriches the theoretical framework of DeFi and sheds light on the relationship between DeFi and DEX. A DEX relies on the liquidity of DeFi, with higher liquidity on the blockchain, the DEX liquidity is expected to be higher, leading to slippage, which means the loss that users suffer when trading on DEX, is reduced. This research provides new insights into understanding the liquidity dynamics of DEXs, extending existing theory on the interplay between liquidity and transaction costs.
References Zarifis A. & Yao Y. (2025) ‘External factors that affect the adoption of decentralized exchanges (DEX) for cryptocurrencies: The case of Curve DEX’ In Zarifis A. & Cheng X. (eds.) Fintech and the Emerging Ecosystems – Exploring Centralised and Decentralised Financial Technologies, Springer: Cham. https://doi.org/10.1007/978-3-031-83402-8_7
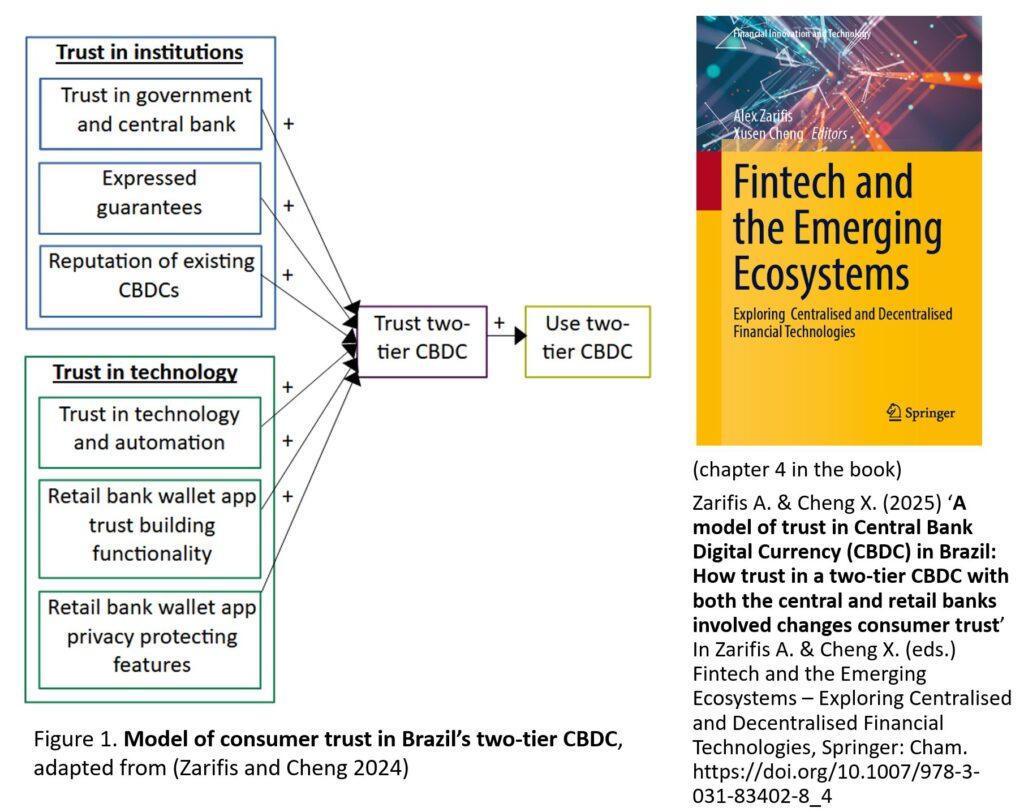
(chapter 4 in book) Central bank digital currencies (CBDC) have been implemented by some countries and trialled by many more. As the name suggests, the fundamental characteristics are that this is money that is digital, without a physical note or coin, and issued by a central bank. The consumer has an increasing range of financial services to choose from including decentralised blockchain based cryptocurrencies. A CBDC may use blockchain technology, but it is centralized, so the institutions that support it play an important role. While being centralised may reduce some risks, it may inadvertently increase others. Despite the centralised top-down nature of this financial technology, it still needs to be adopted so the consumer’s perspective, particularly their trust in it, is very important. Each CBDC implementation can be different, and each country’s context can be different, therefore it is important to understand each case separately. This research models the Brazilian consumer’s trust in their two-tier CBDC, where the central bank and the retail banks retain their current role (Zarifis and Cheng, 2025). This implementation is not a one tier solution where retail banks are bypassed in some ways, and the citizen interacts mostly with the central bank. Existing research that identified six ways to build trust in a different CBDC (Zarifis and Cheng, 2024) was used as a basis. This research tested a model with one additional way to build trust, but this additional way to build trust was not supported. The seventh hypothesized way that is not supported is that the implementation process, including pilot implementations, would build trust. Therefore, despite the differences in the Brazilian CBDC, the original model applies here also which suggests the model applies for both two-tier solutions, and mixed one and two-tier solutions.
Figure 1. Model of consumer trust in Brazil’s two-tier CBDC, adapted from (Zarifis and Cheng 2024)
Three institutional, and three technological factors, are found to play a role. The six ways to build trust that are supported are: (a) Trust in government and central bank offering the CBDC, (b) expressed guarantees for those using it, (c) the favourable reputation of other active CBDCs, (d) the CBDC technology, the automation and limited human involvement necessary, (e) the trust building features of the CBDC wallet app, and (f) the privacy features of the CBDC wallet app and back-end processes. It is important to develop user centered services in Brazil so that trust is built in the services themselves, and the government institutions that deliver them, sufficiently for broad adoption.
References Zarifis A. & Cheng X. (2024) ‘The six ways to build trust and reduce privacy concern in a Central Bank Digital Currency (CBDC)’. In Zarifis A., Ktoridou D., Efthymiou L. & Cheng X. (ed.) Business digital transformation: Selected cases from industry leaders, London: Palgrave Macmillan, pp.115-138. https://doi.org/10.1007/978-3-031-33665-2_6 (open access)
Zarifis A. & Cheng X. (2025) ‘A model of trust in Central Bank Digital Currency (CBDC) in Brazil: How trust in a two-tier CBDC with both the central and retail banks involved changes consumer trust’ In Zarifis A. & Cheng X. (eds.) Fintech and the Emerging Ecosystems – Exploring Centralised and Decentralised Financial Technologies, Springer: Cham. https://doi.org/10.1007/978-3-031-83402-8_4 (open access)
Different organizations see this period of transition and adjustment as either an opportunity or a threat. Some from outside the financial sector such as bigtech see it as an opportunity to take market share. Others have managed to limit competition and have regulatory ‘moats’ around the financial services they provide, that they would prefer to maintain. Whether an existing financial organization decides to keep their existing model, disrupt themselves in a drastic way, or evolve gradually into a new business model, it is important that they understand this multifaceted transformation. While startups are like agile speedboats that can change direction easily, large financial organizations more closely resemble large cruise ships that need to know where they will be in five years’ time, before setting a course to get there.
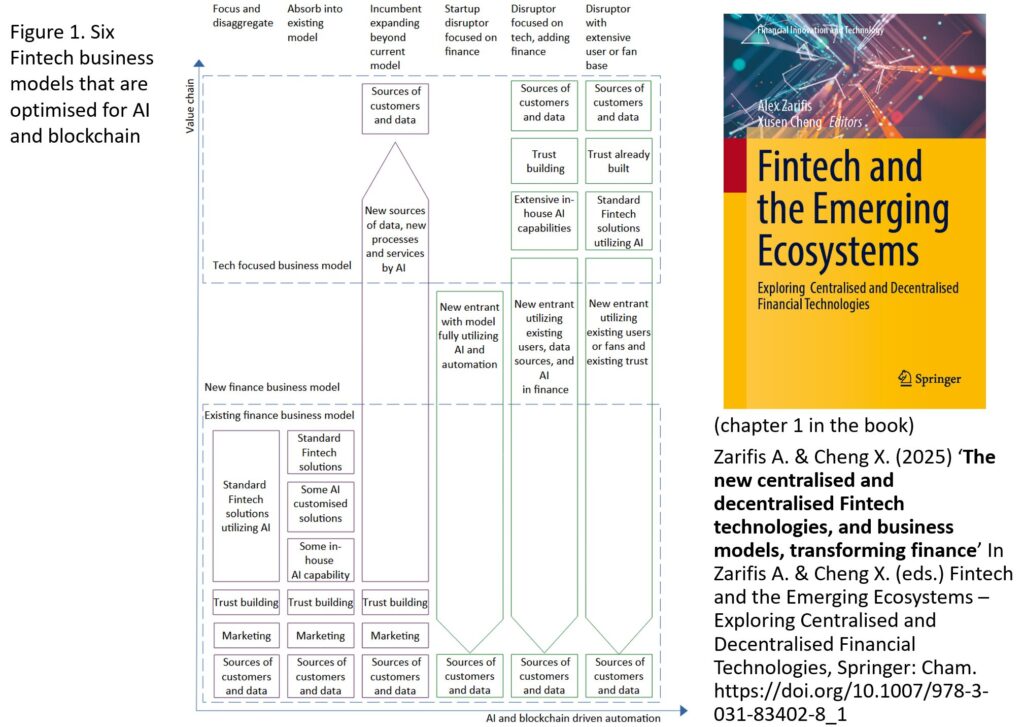
This research finds support for six Fintech business models that are optimised for AI and blockchain. These are (1) focus on less financial services and disaggregate, (2) absorb AI into existing financial model, (3) incumbent in finance expanding beyond current model, (4) new dedicated startup in finance disrupting the established ways of operating, (5) tech company disrupting finance, (6) disruptor not focused on technology with extensive user-base. The first three models involve organizations that are already active in the finance sector. The last three models are new organizations using AI to start offering financial services.
While the sixth model has similarities to the fifth, it also has some distinct features. The key characteristics are that it has an existing user base, with which trust has already been built, and unlike the fifth model, it uses advanced but commoditised financial technology. Despite the ongoing innovation, some Fintech transitioning into a commoditised service, that is easily deployed, is a sign of a maturing sector.
Figure 1. Six Fintech business models that are optimised for AI and blockchain
It is important to appreciate that existing trust with customers or fans, or the ability to build trust, are important parts of the value chain. Having the capability to build trust can be the starting point, with financial services added to it. Is the technology still the most critical factor in a Fintech at this stage, or the ability to build trust in it? Words such as modularity and ecosystem are often used, but it is important to understand how a new Fintech can be created, its journey and how it can build momentum and carve out a niche with technology and trust.
Reference: Zarifis A. & Cheng X. (2025) ‘The new centralised and decentralised Fintech technologies, and business models, transforming finance’ In Zarifis A. & Cheng X. (eds.) Fintech and the Emerging Ecosystems – Exploring Centralised and Decentralised Financial Technologies, Springer: Cham. https://doi.org/10.1007/978-3-031-83402-8_1
E-government can utilise the many new technologies to offer better services. Given the potential benefits of e-government, it is crucial to understand how to successfully achieve agile responses with e-government systems. An agile response in e-government, is when government employees use technology and are very effective in their role. The transformation of technology and collaboration methods, driven by the e-government systems, forces government employees to reconsider their daily workflow and collaboration with colleagues.
Despite the extensive existing knowledge of technology usage and collaboration, there are limitations in explaining the synergy between technology usage and group collaboration in achieving agile responses, from the perspective of government employees.
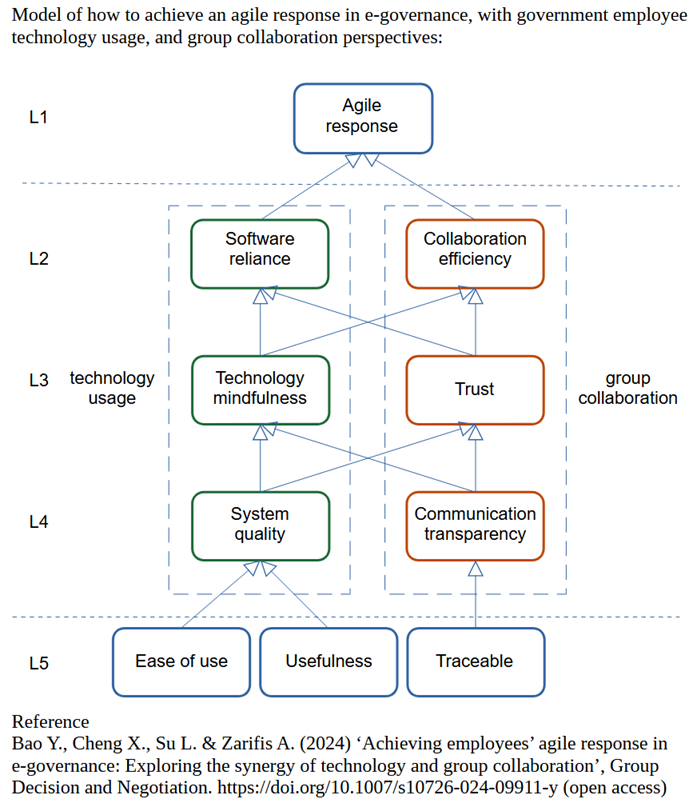
To address these challenges, this study provides a holistic understanding of the successful pathway to an agile response in e-governance, from the perspective of government employees. Two parallel paths are needed to achieve an agile response in e-governance. This study identifies five layers of mechanisms that lead to an agile response in e-governance, considering both the government-employee technology usage path, and the group collaboration path.
Figure 1. Model of how to achieve an agile response in e-governance
The dual pathways are as follows: Level 5 is positioned at the bottom of the model. It includes the fundamental factors that contribute to an agile response in e-governance, including ease of use, usefulness, and being traceable. Traceable in this context is more related to government employees’ work flow.
Levels 2, 3, and 4, are the intermediate factors, which play a bridging role, and are mainly composed of system quality, technology mindfulness, software reliance, communication transparency, trust, and collaboration efficiency. Specifically, system quality, technology mindfulness, and software reliance belong to the government employee technology usage pathway, while communication transparency, trust, and collaboration efficiency belong to the government employee collaboration pathway.
Level 1, at the top of the model is the ultimate goal, an agile response in e-governance. This research shows that to achieve an agile response in e-government, both the perspective of government employee technology usage, and the perspective of group collaboration efficiency must be taken into account.
Reference Bao Y., Cheng X., Su L. & Zarifis A. (2024) ‘Achieving employees’ agile response in e-governance: Exploring the synergy of technology and group collaboration’, Group Decision and Negotiation. https://doi.org/10.1007/s10726-024-09911-y (open access)
While ride-hailing platforms such as Didi, Uber, and Lyft have been with us for some years, it is an innovation that is still evolving, and customers beliefs on it, are still evolving also. Some are happy to use it, while others have some reservations.
Promoting the passengers’ trust in platform and customer citizenship behaviour (CCB) is both challenging and important. It refers to voluntary and discretionary behaviours that are not required for the successful production or delivery of the service, but that help the organization offering the service overall. In ride-hailing services, customer citizenship behaviour (CCB) is the voluntary behaviour of passengers, which is not necessary for the process of ride-hailing services.
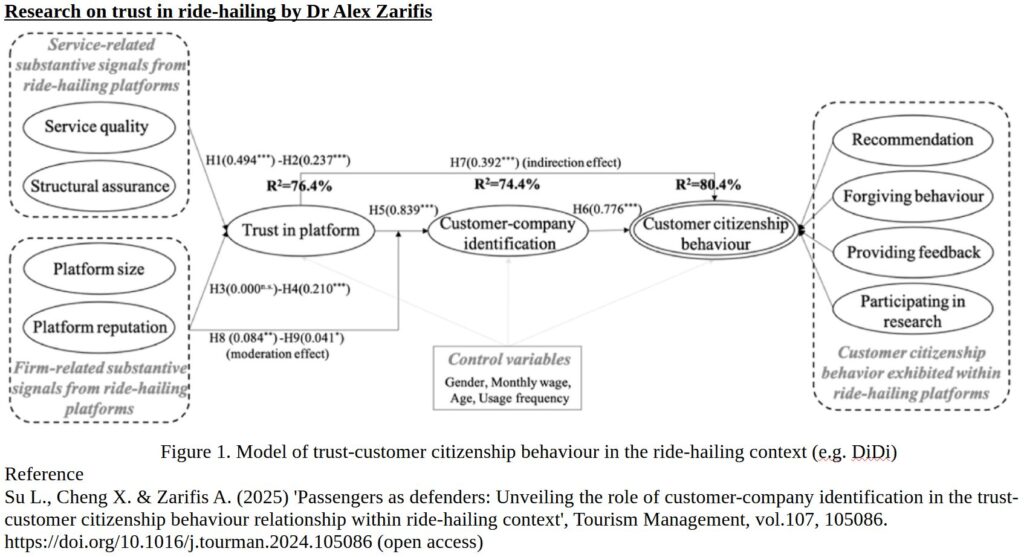
This study looks at three aspects of the relationship of passengers’ trust in platform and customer citizenship behaviour (CCB): (1) What are the signals sent by the ride-hailing platforms that impact passengers’ trust in platform? (2) What are the dimensions of customer citizenship behaviour in the context of ride-hailing? (3) How does passengers’ trust in ride-hailing platforms influence their customer citizenship behaviour towards the platforms? The outcome of this research is the trust-customer citizenship behaviour (CCB) model in the ride-hailing context shown in figure 1.
The findings reveal that platforms can foster passengers’ trust by sending service-related signals (i.e., service quality and structure assurance) and a firm-related signal (i.e., platform reputation). Customer-company identification (CCI) mediates the relationship between passengers’ trust and customer citizenship behaviour (CCB), where passengers engage in CCB by providing recommendations, exhibiting forgiving behaviour, and providing feedback. Customer-company identification (CCI), is related to social identity theory, and refers to the positive and emotional attachment that passengers feel towards the values and concepts of a ride-hailing platform.
Additionally, firm-related signals, including platform size and reputation, enhance the positive relationship between trust and customer-company identification (CCI). These findings contribute to the body of knowledge on trust, customer citizenship behaviour (CCB), and signalling theory, and offer practical guidance to ride-hailing platforms.
Understanding how to build trust, and the specific benefits of a trusting relationship, encourages ride-hailing companies to work harder to build trust better. It also shows customers of these services the power they have, and how important they are to the success of these companies.
Reference Su L., Cheng X. & Zarifis A. (2025) ‘Passengers as defenders: Unveiling the role of customer-company identification in the trust-customer citizenship behaviour relationship within ride-hailing context’, Tourism Management, vol.107, 105086. https://doi.org/10.1016/j.tourman.2024.105086 (open access)
Generative AI (GenAI) has seen explosive growth in adoption. However, the consumer’s perspective in its use for financial advice is unclear. As with other technologies that are used in processes that involve risk, trust is one of the challenges that need to be overcome. There are personal information privacy concerns as more information is shared, and the ability to process personal information increases.
While the technology has made a breakthrough in its ability to offer financial insight, there are still challenges from the users’ perspective. Firstly there is a wide variety of different financial questions that are asked by the user. A user’s financial questions may be specific such as ‘does stock X usually give a higher dividend than stock Y’, or vague, such as ‘how can my investments make me happier’. Financial decisions often have far reaching, long term implications.
Figure 1. Model of building trust in advise given by Generative AI, when answering financial questions
This research identified four methods to build trust in Generative AI in both of the scenarios, specific and vague financial questions, and one method that only works for vague questions. Humanness has a different effect on trust in the two scenarios. When a question is specific, humanness does not increase trust, while (1) when a question is vague, human-like Generative AI increases trust. The four ways to build trust in both scenarios are: (2) Human oversight and being in the loop, (3) transparency and control, (4) accuracy and usefulness, and finally (5) ease of use and support. For the best results all the methods identified should be used together to build trust. These variables can provide the basis for guidelines to organizations in finance utilizing Generative AI.
A business providing Generative AI for financial decisions must be clear what it is being used for. For example analysing past financial performance to attempt to predict future performance is very different to analysing social media activity. The advise of Generative AI needs to feel like a fully integrated part of the financial community, not just a system. Trust must be built sufficiently to overcome the perceived risk. The findings suggest that the consumer will not follow the ‘pied piper’ blindly, however alluring ‘their song’ of automation and efficiency is.
Reference Zarifis A. & Cheng X. (2024) ‘How to build trust in answers given by Generative AI for specific, and vague, financial questions’, Journal of Electronic Business & Digital Economics, pp.1-15. https://doi.org/10.1108/JEBDE-11-2023-0028 (open access)
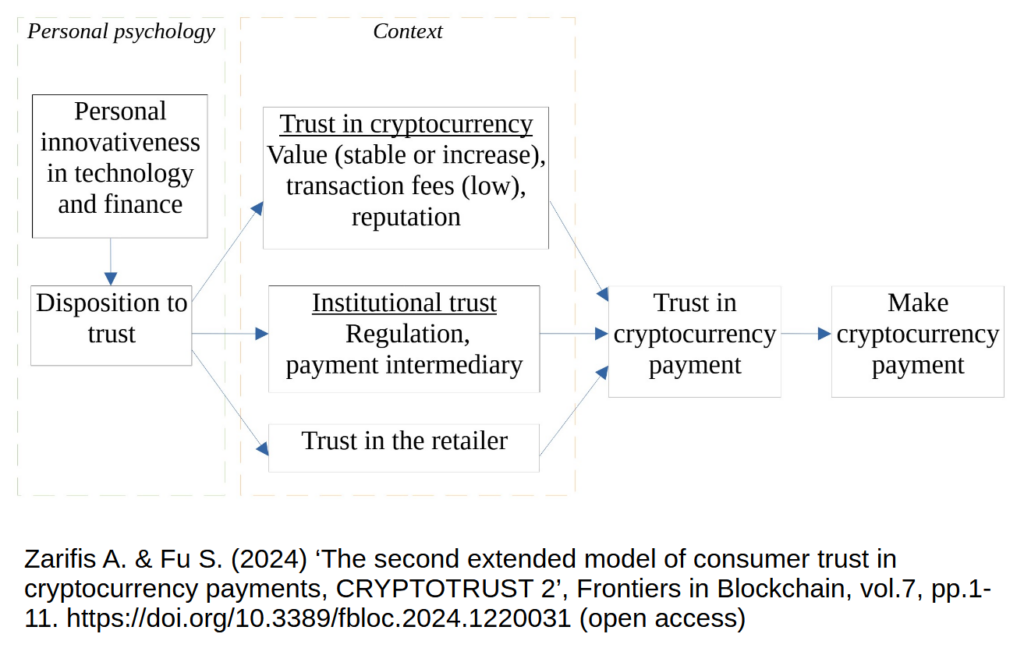
Cryptocurrencies’ popularity is growing despite short-term fluctuations. Peer-reviewed research into trust in cryptocurrency payments started in 2014 (Zarifis et al., 2014, 2015). While the model created then is based on proven theories from psychology, and supported by empirical research, a-lot has changed in the past 10 years. This research re-evaluates and extends the first model of trust in cryptocurrencies and delivers the second extended model of consumer trust in cryptocurrencies CRYPTOTRUST 2 (Zarifis & Fu, 2024) as seen in figure 1.
Figure 1: The second extended model of consumer trust in cryptocurrencies (CRYPTOTRUST 2)
Trust in a cryptocurrency is a multifaceted issue. While some believe that the consumer does not need to trust cryptocurrencies because they utilize blockchain, most people appreciate that you must trust cryptocurrencies, just as you must trust any other technology you use that involves some risk.
The first three variables of the model come from the individual’s psychology: Personal innovativeness is divided into (1) personal innovativeness in technology and (2) personal innovativeness in finance. These two influence (3) personal disposition to trust.
There are then six variables that come from the specific context, and not the person’s psychology: The first three are related to the cryptocurrency itself. These are (4) the stability in the cryptocurrency value, (5) the transaction fees and (6) reputation. Institutional trust is shaped by (7) regulation and (8) payment intermediaries that may be involved in fulfilling the transaction. The last contextual factor is (9) trust in the retailer. The six variables from the context influence (10) trust in the cryptocurrency payment which then, finally, influences (11) the likelihood of making the cryptocurrency payment.
Separating personal innovativeness to personal innovativeness in (1) technology and (2) finance, is a useful distinction as some consumers may have different levels of personal innovativeness for technology and finance. The analysis here supports that these are separate constructs.
This research shows that trust in cryptocurrencies has not changed fundamentally, but it has evolved. All the main actors in the value chain still play a role in building trust. There is more emphasis from the consumer on having a stable value and low transaction fees. This may be because consumers now have more experience with cryptocurrencies, and they are better informed. It may also be because there are more cryptocurrencies available, and other alternatives such as Central Bank Digital Currencies (CBDC), so consumers can review the many alternatives and try to identify the best one.
References
Zarifis A., Cheng X., Dimitriou S. & Efthymiou L. (2015) ‘Trust in digital currency enabled transactions model’, Proceedings of the Mediterranean Conference on Information Systems (MCIS), pp.1-8. https://aisel.aisnet.org/mcis2015/3/
Zarifis A., Efthymiou L., Cheng X. & Demetriou S. (2014) ‘Consumer trust in digital currency enabled transactions’, Lecture Notes in Business Information Processing-Springer, vol.183, pp.241-254. https://doi.org/10.1007/978-3-319-11460-6
Zarifis A. & Fu S. (2024) ‘The second extended model of consumer trust in cryptocurrency payments, CRYPTOTRUST 2’, Frontiers in Blockchain, vol.7, pp.1-11. https://doi.org/10.3389/fbloc.2024.1220031 (open access)
By Dr Alex Zarifis, originally published in The Conversation
I have a confession to make. Despite being an academic, I do not actually read many books. In truth, I don’t often find books about what I like. My interest is on how the latest technologies affect business, and this topic is usually covered better by research articles and the press.
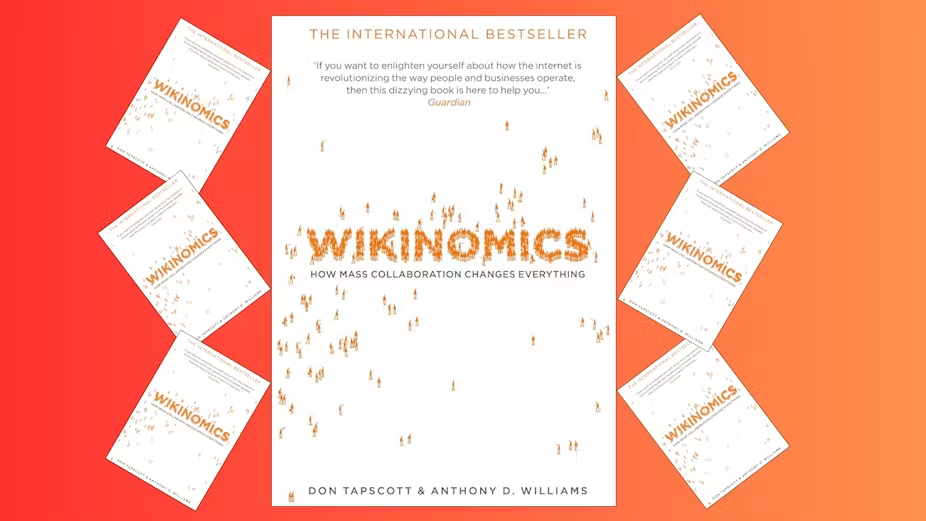
In the days when I was a student and money was tight, I was even less likely to buy books. But one exception was Wikinomics: How Mass Collaboration Changes Everything (2006). Written by Canadian tech thinkers Dan Tapscott and Anthony D. Williams, it captured my interest in how new innovations can change our personal and professional lives – and how exciting this change can be. Clearly I was by no means the only one that felt this way, as the book became a tremendous success.
The title, a compound of Wikipedia pages and economics, followed in the style of the equally successful Freakonomics (2005), but Wikinomics is very much a landmark in its own right. What it conveyed powerfully was that the level of mass collaboration and sharing online was about to move way beyond what we had seen in the first 15 years of the internet, transforming how people did business.
These were much more than mere technological advances, the book argued, and would require a completely different business mindset and philosophy. This was all about openness, sharing, freedom to innovate, and acting globally.
Wikinomics highlights seven new models of collaboration:
1. Open-source software: Software whose source code is made available for everyone to use and build on, which provides a way for firms and coders to coalesce around the same standard. One of the key early driving forces was the Linux operating system, while the book also points to Wikipedia as the archetypal example of the collaborative mindset.
Today, we see many examples of standalone coders coming together from around the world to build applications that are decentralised, meaning they’re not owned by anyone or based anywhere. Decentralised finance (defi), for instance, is offering a new way for people to do everything from trading financial assets to taking out mortgages.
2. Crowdsourcing innovative talent: This allows organisations to solve problems with ideas from outside, typically from other parts of the world. The example given in the book is InnoCentive (now Wazoku Crowd), a site where organisations post scientific challenges and offer rewards for their solution.
3. Prosumers: These are forward-thinking consumers who co-create products and services. In 2006, for instance, users of the virtual world, Second Life, were creating virtual buildings then renting them to other users. Today, fans of computer games such as Total War: Warhammer III are creating new characters and environments in a similar way.
4. Innovators sharing information: Making data widely available for others to use has particular importance in helping solve humanity’s greatest challenges, such as climate change. The increasing popularity of open-access publishing of academic research has been an important step in this direction.
5. Open platforms: Software that allows largely unrestricted access to its content and data gives businesses and individuals more room to collaborate and create new products. One example in the book is Google Maps, which was used by US entrepreneur Paul Rademacher to create a service called HousingMaps. It took data from Craigslist about homes for sale in a given area and pinned them on a map so that anyone searching for a home could see all the available locations at the same time.
Combining capabilities in this way became known as mash-ups, and can be seen today in a service like online bank Revolut. Revolut brings together services and information from a broad variety of organisations and offers them in an integrated way that is easy to use.
6. Mass collaboration in manufacturing: The book noted how a manufacturer like Boeing had shifted from designing everything in-house and sourcing specified parts from individual suppliers to instead having suppliers working together to design parts themselves and then assemble them in teams in Boeing factories.
This switch in emphasis from supply chains to ecosystems has more recently been typified by Shenzhen in China, where collaborative manufacturing in everything from circuits to touchscreens blurs the boundaries between the companies involved.
7. Modern workplaces that avoid hierarchies and silos: Instead of rigid structures, the driving force is social connectivity and fun.
Pros and cons
As is often the case with hugely successful books, Wikinomics was a combination of a great title, good writing and timing. By 2006 many of these trends were well underway. For instance, it was already common for coders to use open-source software like Linux for mass global collaboration. But if the book had been more original, it would not have been so well timed for mass market appeal.
A common criticism of Wikinomics is that it created many obscure terms that will only be familiar to those who have read the book. For example, its fourth collaborative model is called “ideagoras”, which hasn’t exactly caught on. No doubt the authors could have used simpler existing terms, but this is not the main weakness of the book.
With the benefit of hindsight, Wikinomics emphasised the positives of mass collaboration but did a poor job of foreseeing the challenges. Openness has made the world much more vulnerable to cybersecurity hacks, frauds and privacy breaches. Our behaviour online is now endlessly recorded and analysed, making people feel both distrustful and powerless.
What the book did do very well was to frame the issues around the new collaborative economy and explain them clearly. It helped readers to organise the new and old information in their minds, making it easier for them to analyse developments and be part of the revolution.
As a lecturer that teaches business on an executive MBA course to experienced managers, this is something I can appreciate. I cannot always tell them something they have not heard before, but if I can frame the issues well and communicate them clearly, it’s still useful to them. This is ultimately what Wikinomics did: it helped clarify the issues readers already had some understanding of, helping to shape the business zeitgeist for web 2.0.
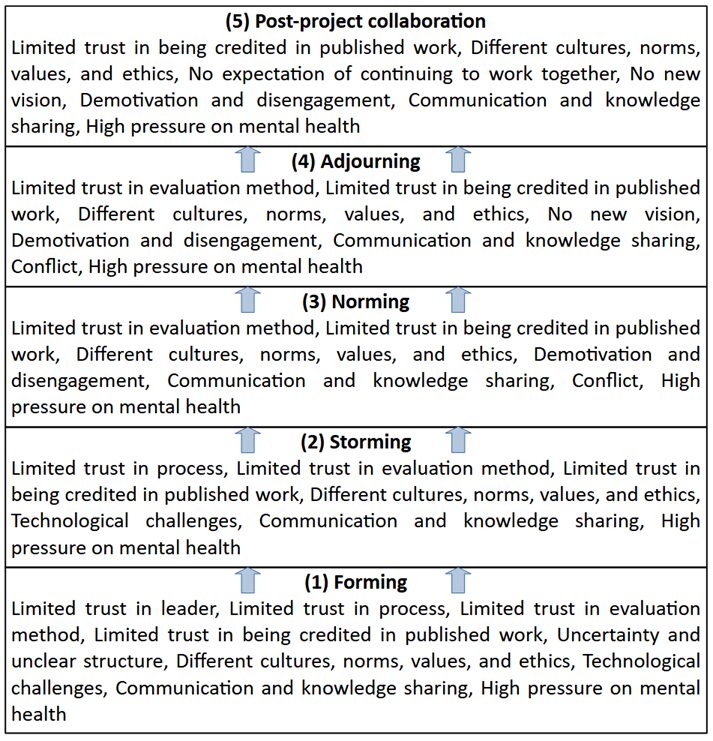
There are many benefits for researchers that take part in a project but there are also several challenges that can create a cumulative, negative, effect on their mental health. This research identifies the challenges researchers face in projects, so that the leader of the project can reduce them as far as possible.
Existing research focuses on four stages of a project: Forming, Storming, Norming and Adjourning. This research adds a fifth stage, Post-Project Collaboration, as this stage is implicitly or explicitly a part of most research projects. For example, a post-doctoral researcher expects to be credited for their work even if it is published after the end of the project. The specific challenges for each of the five stages are identified. This enables the leader to focus on a manageable number of challenges at each stage.
Some challenges are in only in one stage of the process, while other challenges are across several stages. It is notable that there is no conflict at the start, but trust is a challenge at the start. This suggests that low trust at the start causes problems later. Therefore, there is a delayed reaction, and once the conflict happens it might be too late, as the trust should have been built earlier.
Figure 1: A model for reducing the challenges for researchers in projects across five stages
Trust is important in several collaboration settings, particularly at the start, until participants familiarise themselves with each other and the project team matures. In research teams, due to the long period of time until the research is published, often over five years, there is an additional, long-term cause for risk and distrust that is only resolved once the research is published.
Trust should be built during the first stage to cover four specific topics: Trust in the leader, process, evaluation method, and trust in being credited in published work.
In the final two stages of the project, adjourning and post-project collaboration, a new vision needs to be communicated effectively as the original vision stops resonating after the norming stage.
For those challenges that cannot be solved outright, the leader of the research project must show an awareness. The leader should be ambidextrous, in the sense of focusing on the project deliverables and the socio-psychological aspects of the teamwork.
Reference
Zarifis A. & Cheng X. (2024) ‘A model reducing researchers’ challenges in projects: build trust first for better mental health’, Cogent Business & Management, vol.11., no.1, pp.1-13. https://doi.org/10.1080/23311975.2024.2350786 (open access)
Financial technology often referred to as Fintech, and sustainability are two of the biggest influences transforming many organizations. However, not all organizations move forward on both with the same enthusiasm. Leaders in Fintech do not always prioritize operating in a sustainable way. It is, therefore, important to find the synergies between Fintech and sustainability.
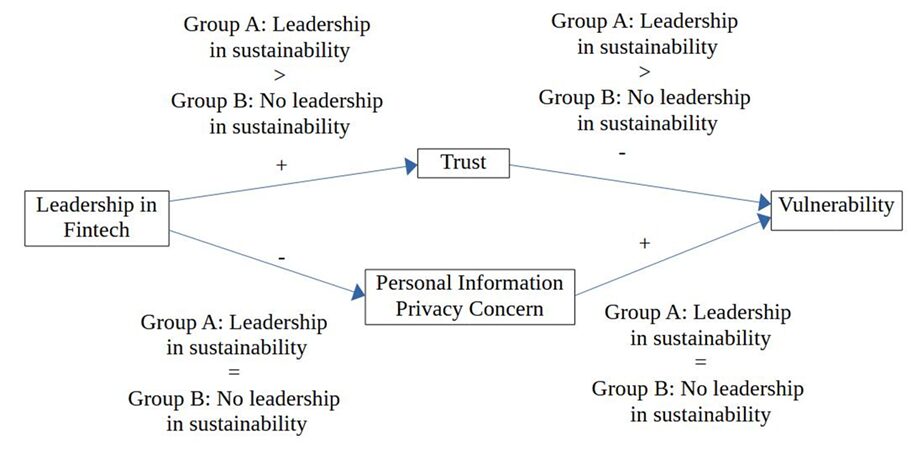
One important aspect of this transformation many organizations are going through is the consumersʹ perspective, particularly the trust they have, their personal information privacy concerns, and the vulnerability they feel. It is important to clarify whether leadership in Fintech, with leadership in sustainability, is more beneficial than leadership in Fintech on its own.
This research evaluates consumers’ trust, privacy concerns, and vulnerability in the two scenarios separately and then compares them. Firstly, this research seeks to validate whether leadership in Fintech influences trust in Fintech, concerns about the privacy of personal information when using Fintech, and the feeling of vulnerability when using Fintech. It then compares trust, privacy concerns and vulnerability in two scenarios, one with leadership in both Fintech and sustainability, and one with leadership just in Fintech without sustainability.
Figure 1. Leadership in Fintech, trust, privacy and vulnerability, with and without sustainability
The findings show that, as expected, leadership in both Fintech and sustainability builds trust more, which in turn reduces vulnerability more. Privacy concerns are lower when sustainability leadership and Fintech leadership come together; however, their combined impact was not found to be sufficiently statistically significant. So contrary to what was expected, privacy concerns are not reduced more effectively when there is leadership in both together.
The findings support the link between sustainability in the processes of a Fintech and being successful. While the limited research looking at Fintech and sustainability find support for the link between them by taking a ‘top‐down’ approach and evaluating Fintech companies against benchmarks such as economic value, this research takes a ‘bottom‐up’ approach by looking at how Fintech services are received by consumers.
An important practical implication of this research is that even when there is sufficient trust to adopt and use Fintech, the consumer often still feels a sense of vulnerability. This means the leaders in Fintech must not just think about how to do enough for the consumer to adopt their service, but they should go beyond that and try to build trust and reduce privacy concerns to the degree that the consumer’s belief that they are vulnerable is also reduced.
These findings can inform a Fintech’s business model and the services it offers consumers.
Reference
Zarifis A. (2024) ‘Leadership in Fintech builds trust and reduces vulnerability more when combined with leadership in sustainability’, Sustainability, 16, 5757, pp.1-13. https://doi.org/10.3390/su16135757 (open access)
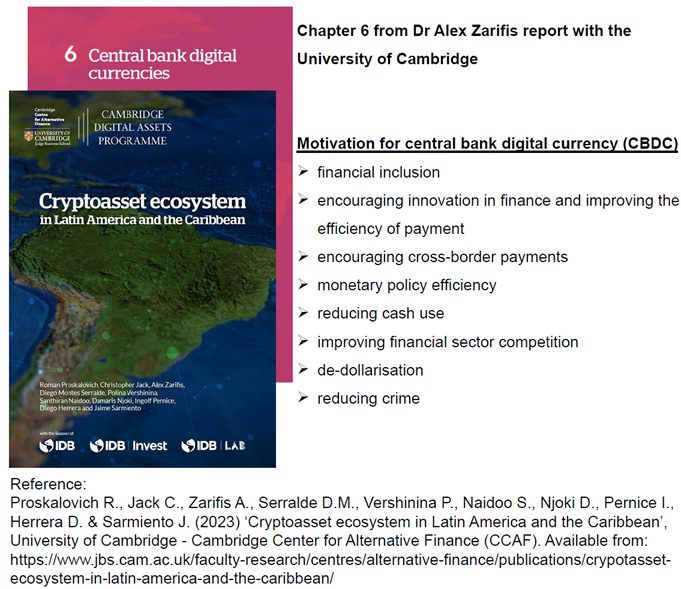
This research is on the state of central bank digital currencies (CBDC) in Latin America. This is the sixth chapter in my report with the University of Cambridge (Proskalovich et al. 2023). I have given a general overview of this report already, so I am just focusing on the chapter on CBDC adoption here.
A CBDC is essentially digital money, issued by a central bank. Unlike most cryptocurrencies that are decentralised, this currency is centralised. This is an important characteristic of the technology that has many implications. For example the central bank may be able to see all the user transactions.
CBDCs can be either wholesale and retail. The general public can use the retail version, while the wholesale version can move large amounts of money between banks. Our research findings suggest that Latin American central banks are focusing mainly on the retail version.
Retail CBDCs can operate with one tier or two tiers. A central bank can issue a one-tier retail digital currency directly to individuals. For the two-tier form, it issues the digital currency to a commercial bank who then offers them to individuals. Most existing implementations in Latin America are hybrid, offering both the one-tier and two-tier forms in parallel. In the hybrid scenario, the user has both a central bank digital wallet, and a retail bank digital wallet.
Figure 1: The motivations behind CBDC adoption in Latin America
These initiatives in Latin America are not completely new. There has been effort to develop and implement them for some time. The first initiative to explore CBDCs was actually back in 2014 in Ecuador. Most countries in Latin America have expressed interest in CBDCs, however, the extent of the engagement varies greatly from (1) exploring the opportunity, to (2) having concluded a pilot project, or (3) launched and available to the public.
There are several motivation behind creating this form of currency. The two main drivers are usually (1) financial inclusion, and (2) encouraging innovation in finance and improving the efficiency of payments. Other popular reasons are encouraging cross-border payments, monetary policy efficiency, reducing cash use, improving financial sector competition, de-dollarisation and reducing crime.
Challenges include (1) a large informal economy and the popularity of cash, (2) limited financial and digital knowledge, (3) lack of identity documents, (4) limited accessibility, (5) power outages and natural disasters, and (6) currency substitution and capital flight. Capital flight happens for several reasons including high inflation and unfavourable economic conditions.
If you want to learn more about this important part of the cryptoasset ecosystem, you can read the third chapter of the report.