The widely used Business Model Canvas identifies nine building blocks of a business model. These nine building blocks did indeed capture the key priorities of a business model for many years. However, with the increasing role of AI and the increasing volume of data it consumes, some additions to these nine building blocks are necessary to bring them up to date.
One more building block is added to capture the increased role of AI and data. The new building block captures the trust-building methods applied, and the methods utilized to reduce privacy concerns. Trust-building is added because of how central trust with all the stakeholders is to utilizing AI. Privacy concerns are important for legal and ethical reasons, but also because if users have these concerns, they will not share their data as willingly. These can be seen as two separate issues, but they are often intertwined. Both trust and privacy concern require a deep understanding of the user’s perspective. Insufficiently addressing trust and privacy can lead to pushback from customers, but also from governments in the form of stricter regulation, thereby negating the benefits of increased use of AI.


Table 1: The updated AI-focused Business Model Canvas with 10 blocks
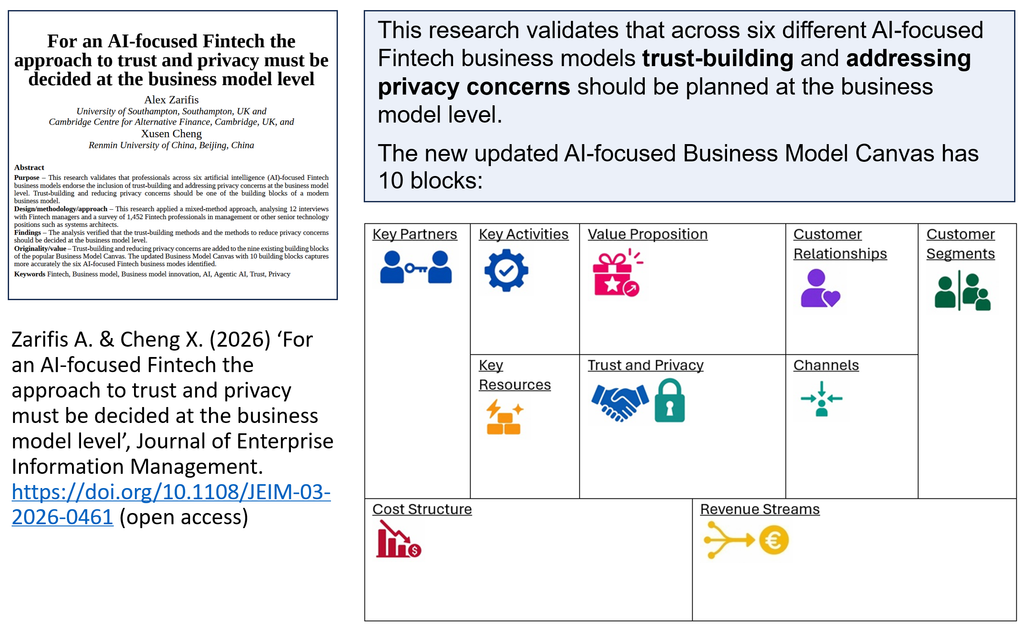
This research tested the new building block against each of the six proven AI-focused business models. The first three models involve organizations that are already active in the financial sector. The last three models are organizations that are new to offering financial services.
With the new building block added to the original Business Model Canvas, the resulting ten building blocks are: (1) value propositions, (2) customer relationships, (3) customer segments, (4) channels, (5) cost structure, (6) revenue streams, (7) key partnerships, (8) key activities, (9) key resources, and (10) how to build trust and reduce privacy concerns. These ten building blocks ensure that the stakeholders in an organization are focused on the most important issues when planning and implementing a new business model (Zarifis & Cheng 2026).

Reference
Zarifis A. & Cheng X. (2026) ‘For an AI-focused Fintech the approach to trust and privacy must be decided at the business model level’, Journal of Enterprise Information Management. https://doi.org/10.1108/JEIM-03-2026-0461 (open access)
This research explores the implications for risk, of six AI-focused Fintech business models, identified in the previous research. While each of the six business models has been validated in previous research, their typical influence on risk has not been sufficiently explored
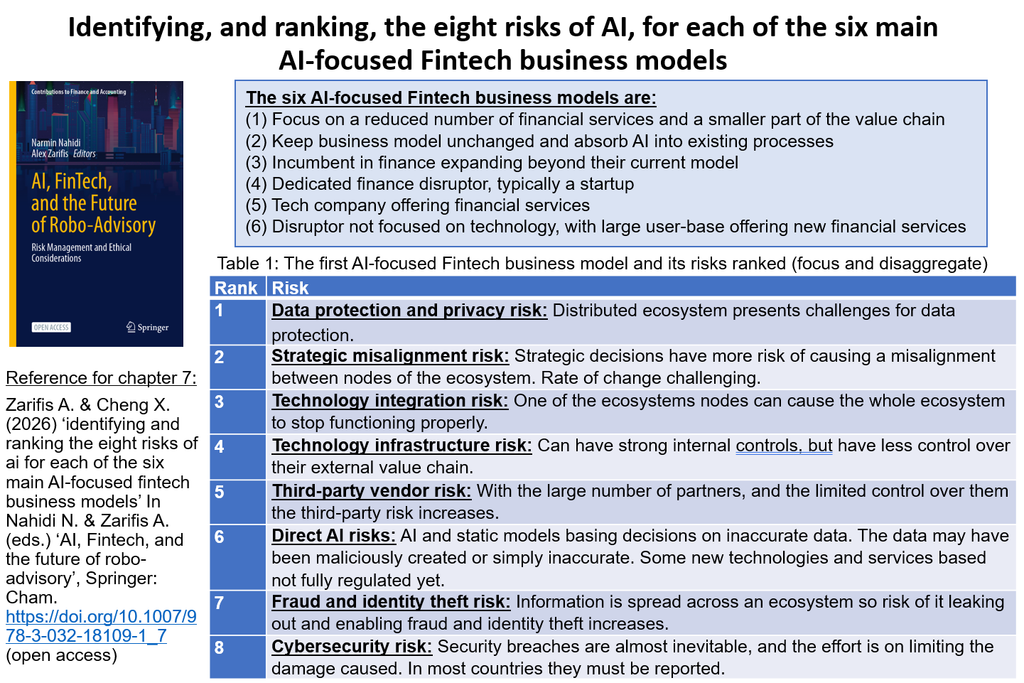
The first three of the six AI-focused finance business models, apply to existing financial companies. These are (1) concentrating on a reduced number of financial services, and a smaller part of the value chain, (2) keeping the business model unchanged, and absorbing AI into existing processes, and (3) expanding beyond their current model, without sacrificing existing services.
The last three AI-focused Fintech business models, apply to organizations that did not previously offer financial services. So, the last three are (4) a dedicated finance disruptor, typically a startup, (5) a tech company offering financial services, and finally (6) is a disruptor not focused on technology, with large user-base offering new financial services.

Table 1. The first AI-focused Fintech business model and its risks ranked (focus and disaggregate)


The eight risks related to the application of an AI-focused business model identified are: (1) Direct AI risks, (2) technology integration risk, (3) third-party vendor risk, (4) technology infrastructure risk, (5) data protection and privacy risk, (6) cybersecurity risk, (7) fraud and identity theft risk, and finally (8) strategic misalignment risk. The eight risks apply to all six models, however, they are not equally significant in all models. For example, in table one we see the ranking of the eight risks for the first AI-focused business model.
The six business models reduce risk in two main ways: Firstly, because they are proven models, and secondly because they have a proven place in the emerging financial ecosystem.
While the Fintech business models do not necessarily increase risk, and may indeed reduce it, because of the change in the nature of the risk involved, trust needs to be built with all the stakeholders.
These are the main findings of this research.

Reference for chapter 7:
Zarifis A. & Cheng X. (2026) ‘Identifying and ranking the eight risks of AI for each of the six main AI-focused Fintech business models’ In Nahidi N. & Zarifis A. (eds.) ‘AI, Fintech, and the future of robo-advisory’, Springer: Cham. https://doi.org/10.1007/978-3-032-18109-1_7 (open access)

Most financial institutions can meet their short-term targets by offering attractive services. However, the best financial institutions go beyond that, and build strong relationships. Both retail customers and organizations, show trust and loyalty to financial institutions they have a stronger bond with. Before the internet, this happened naturally with the face-to-face interaction. Even when we interacted with a company’s systems on the internet, until recently, these systems did not use AI, but human logic coded into them. Now, with the prevalence of AI and financial robo-advisory, new ways are needed to build trust.
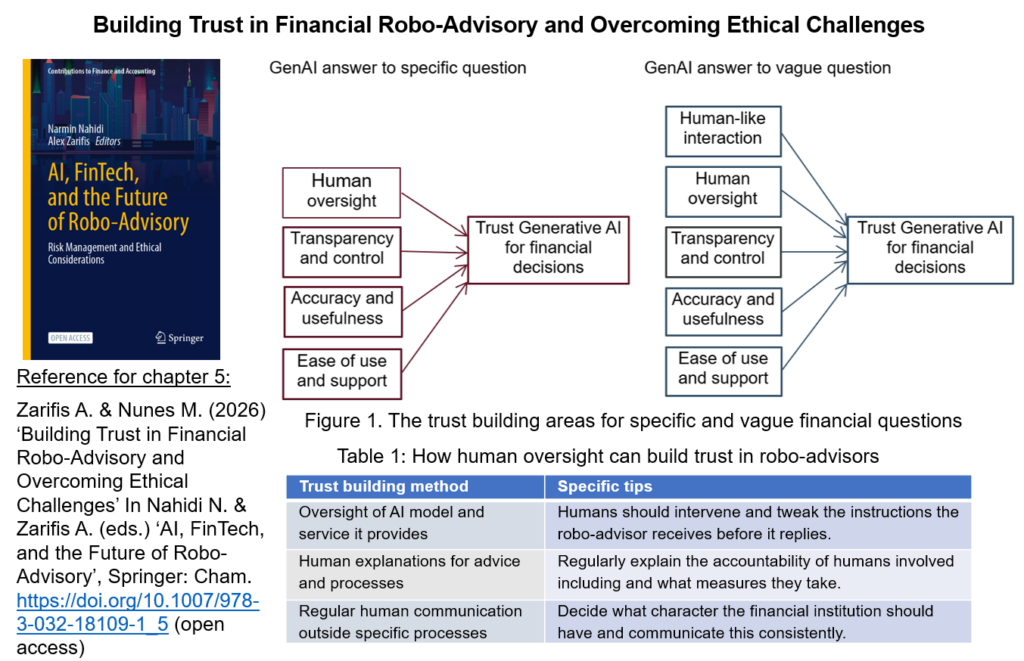
Previous research identified five areas where trust could be built for financial robo-advisors, as illustrated in figure 1. These are building trust with human oversight, with transparency and control, with accuracy and usefulness, by making things easy to use, and finally with a humanlike interaction. This research identifies the specific methods for building trust, for each of these five areas.

Figure 1, the trust building areas for specific and vague financial questions and table 1, building trust with human oversight

Previous research identified five areas where trust could be built for financial robo-advisors, as illustrated in figure 1. This research identifies the specific methods for building trust, for each of these five areas. For example, as illustrated in table 1, building trust with human oversight can be done in three specific ways: (1) Oversight of AI model and service it provides, (2) human explanations for advice and processes, and (3) regular human communication outside specific processes.
Building trust with transparency and control can be done by: (1) Recognizing that there are beliefs that do not immediately lead to action, so following the current data will not give us all the answers, (2) explain actions and demonstrating ability and integrity, and (3) balance automation with control to avoid disempowering users.
Building trust with accuracy and usefulness can be done by having: (1) Accurate and relevant information conveying competence and integrity, (2) useful functionality supported by extensive testing, and multiple methods, and (3) enhanced usefulness through personalisation.
Building trust by making things easy to use can be done by: (1) Making everything easy to use while keeping all the necessary functionality, (2) support time management with nudges, and (3) having a useful and reliable service with high performance.
Building trust with a humanlike interaction can be done by: (1) Utilizing the latest sentiment analysis, and longest contextual memory, (2) the robo-advisor should have a clear persona, and (3) build a relationship, and a feeling of friendship and partnership.

Reference for chapter 5:
Zarifis A. & Nunes M. (2026) ‘Building Trust in Financial Robo-Advisory and Overcoming Ethical Challenges’ In Nahidi N. & Zarifis A. (eds.) ‘AI, FinTech, and the Future of Robo-Advisory’, Springer: Cham. https://doi.org/10.1007/978-3-032-18109-1_5 (open access)